Travel notes from Juba, South Sudan


Amsterdam

Ito and I ended our Italian/French/Netherland vacation (see https://wcoats.wordpress.com/2011/07/23/travels-in-italy-and-france/) in Amsterdam visiting friends (Bill Wirt, Dolph Westerbos, and René van Hell). While there, we enjoyed the usual sights and the coldest July day in the Netherlands (July 24) since 1903! Then Ito took the plane home to Washington DC while I headed on to South Sudan.

While Amsterdam was having its coldest day, Washington was suffering one of its hottest days in history. The same weekend had the only two consecutive days with lows above 84 decrees ever recorded. The high temperature of 105° at 3:52 pm on July 22 at Washington Dulles was a new all-time record, beating the old record for July 22 of 98° in 1998 by 7°. By the 24th Dulles had “cooled” down to a high of 94° (97° at Reagan National).

The average global high may well have been perfectly normal (I couldn’t find such data if it exists), demonstrating that distribution does matter.
Juba, The Republic of South Sudan

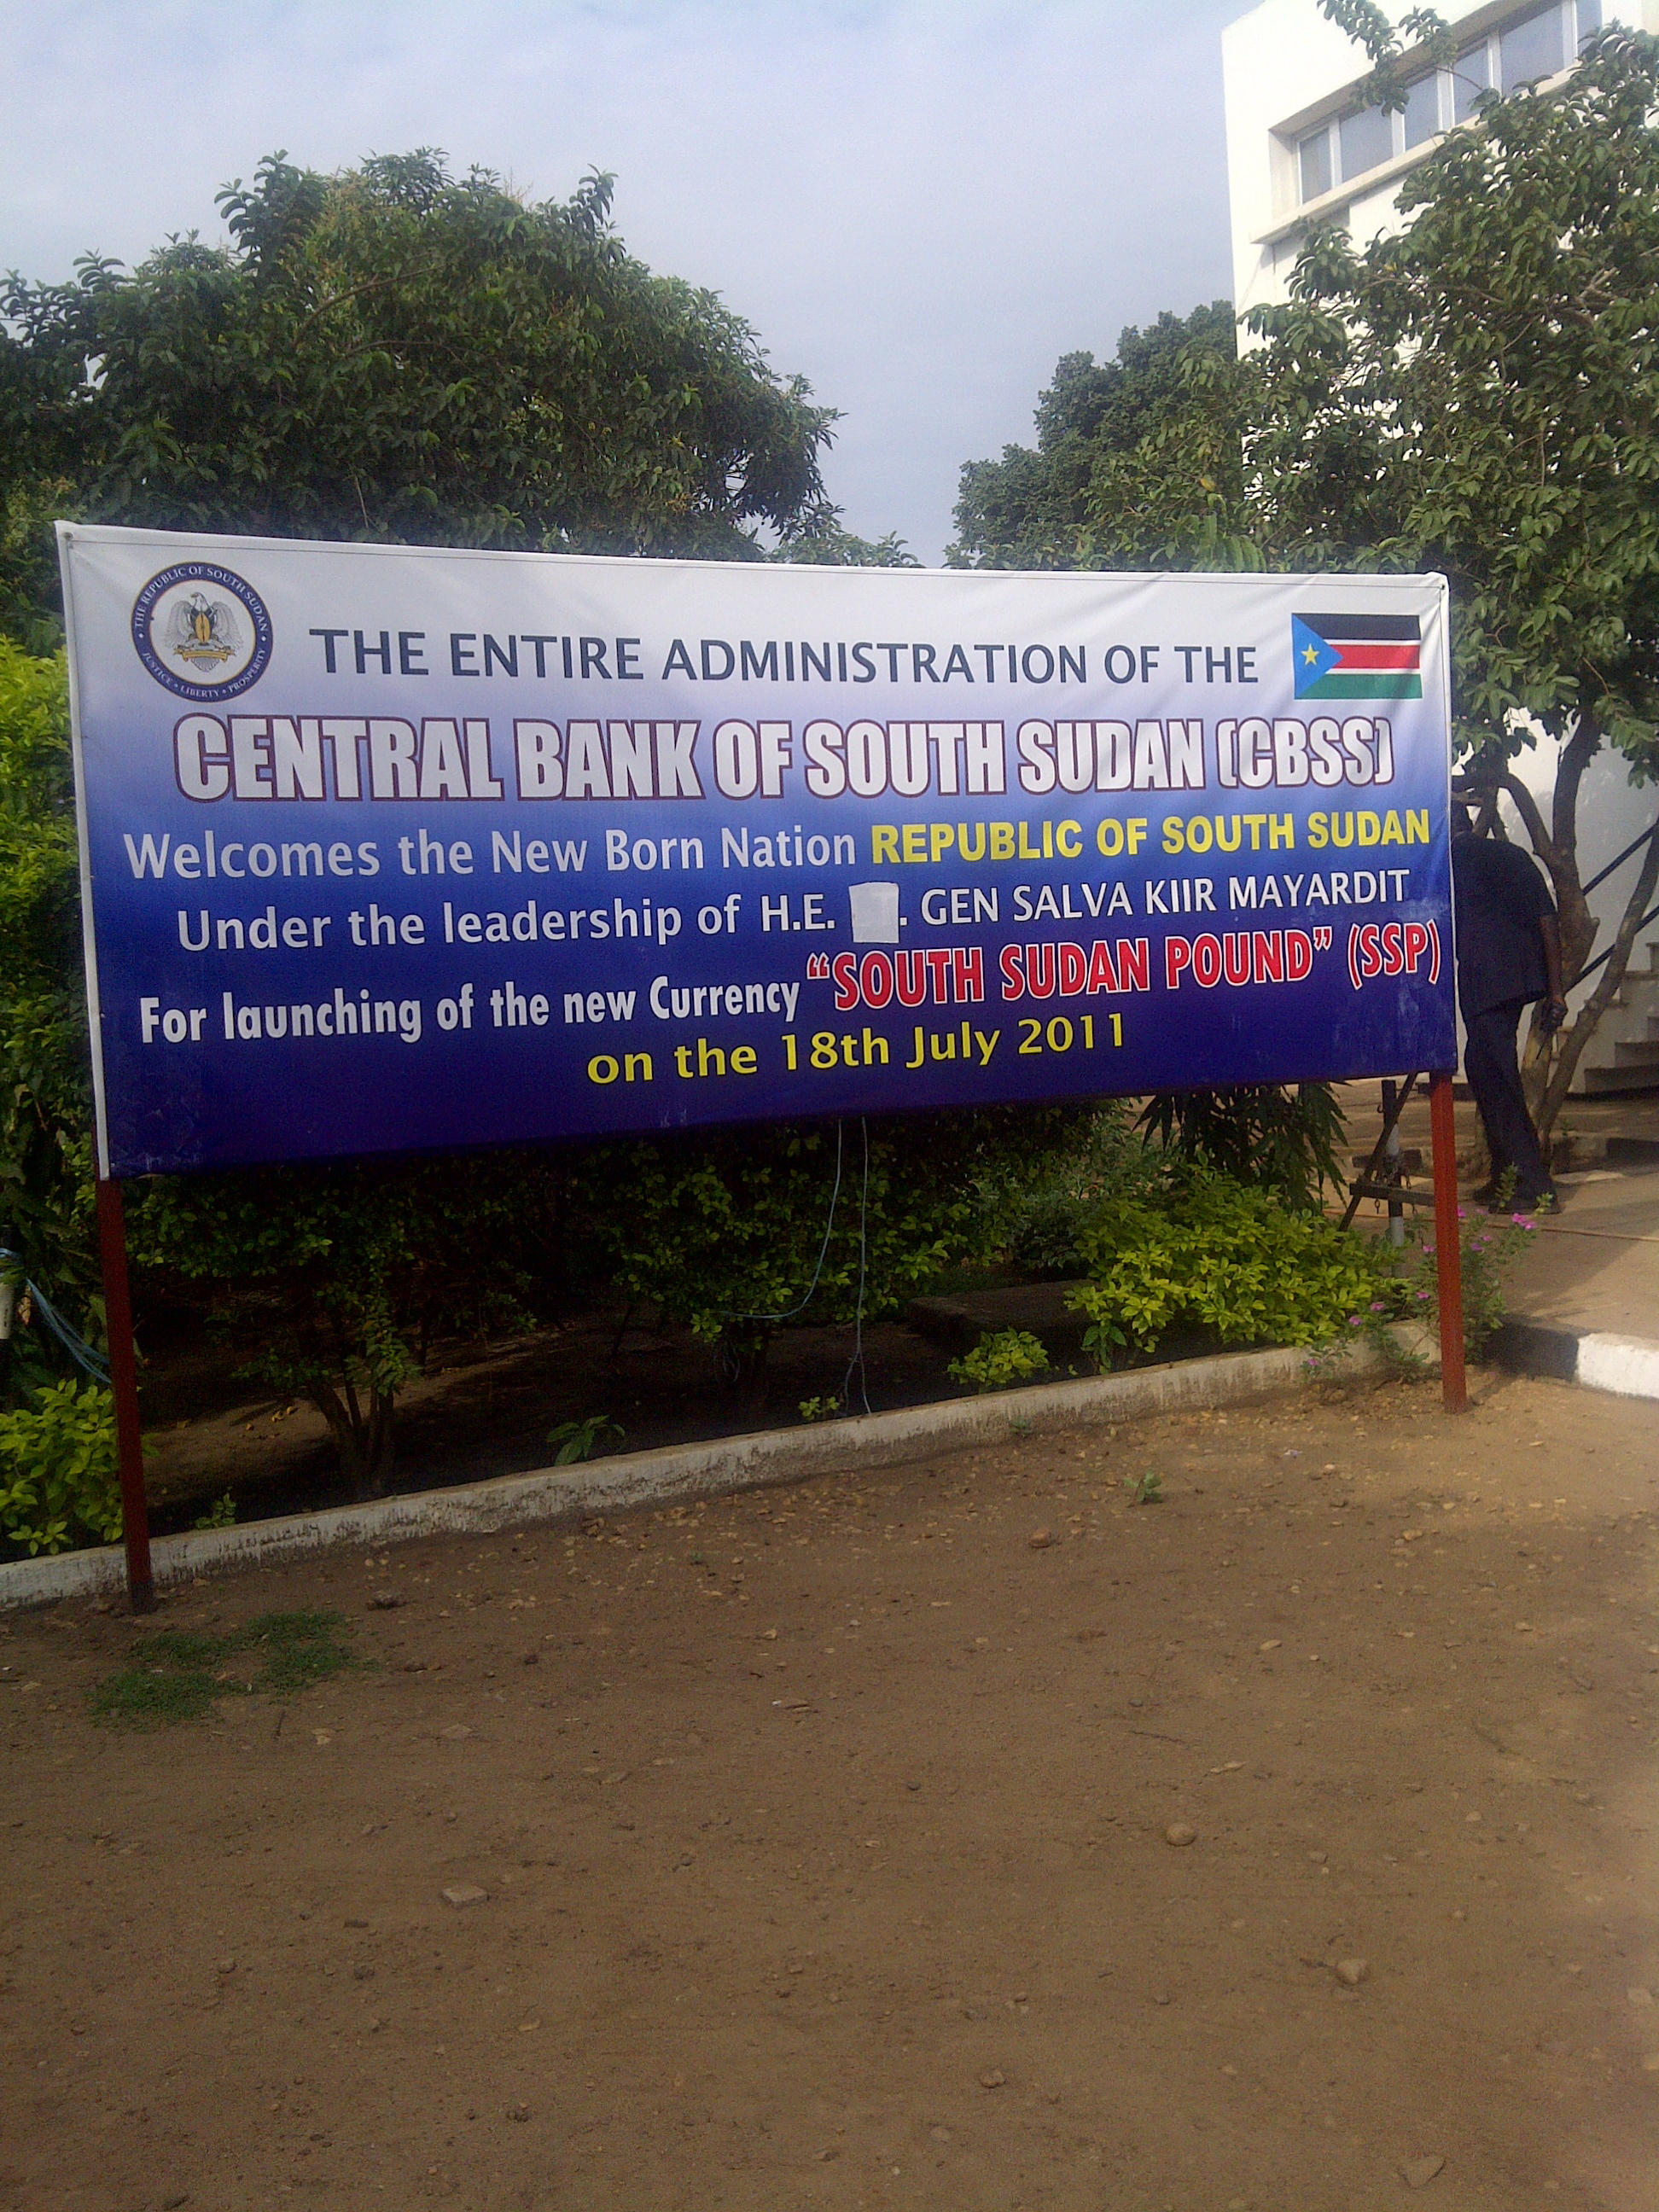
I left Southern Sudan on June 21 and returned on July 27th to the newly independent Republic of South Sudan (on July 9). The introduction of the new South Sudanese Pound (SSP), which our Deloitte team has been helping the local authorities prepare to issue for over a year, had started on July 18th.  The replacement of SDG (Sudanese Pounds) with the new SSP is targeted to be completed by the end of this month (August—a 45 day period).

The establishment of the new Central Bank of South Sudan, though inheriting most of the staff and buildings of the Bank of Southern Sudan (a branch of the Central Bank of Sudan headquartered in the North), is being seriously hampered by the failure so far of the President of the Republic to appoint its new Governor and Board.

The big success on this visit was the launch of foreign exchange auctions after the new central bank law wiped out all of the exchange controls imposed by North Sudan when Southern Sudan was part of it. The Central Bank of Sudan (the central bank for the whole country before the South spit off) was running out of foreign exchange reserves (foreign currency owned by the central bank that it could sell to the market to influence the exchange rate of its currency). It wanted to keep its exchange rate to the U.S. dollar and other foreign currency low so that those holding its currency could buy dollars more cheaply (a so-called “strong” currency). But to do that it had so sell dollars from its foreign currency reserves. When it was running out of dollars, it could no longer support the exchange rate it wanted. So it imposed restrictions on the purposes for which people could buy dollars with the Sudanese Pound (restricting demand) in order to support it’s artificially low (strong) exchange rate. As a result, a spread of up to 1½ percentage points opened up between the official rate and the street (black market) rate.

South Sudan has removed those restrictions and introduced twice weekly auctions of U.S. dollars to the highest bidders. There have been three auctions so far and they are working well as the market gets used to them. The spread between the official and street rate (no longer illegal) has already narrowed to about 25 basis points (a quarter of a percentage point). Today we hit a big bump in the process and the acting governor, responding to political pressure capped the exchange rate for the next auction below the rate of the last one. We expect the announcement of a permanent Governor very soon.

After independence, the Bank of Southern Sudan became the Central Bank of South Sudan (CBSS). The Bank has a fairly large courtyard in the middle where people gather to chat or smoke cigarettes and where the Governor holds large staff meetings. You can see it in the attached picture. I stepped out of my office on to the far edge of the courtyard the other day and was standing next to one of the Bank officials. He was on his cell phone and obviously expecting to meet someone: “Where are you? … You are standing under a tree? … What tree? We have a lot of them.” Every now and then a fairly large monkey drops out of one of them, which always gives me a start.

There seems to be more life around the Bank than before. After all, there is a lot going on (introducing a new currency and starting new foreign currency auctions). Yet the halls of the Bank are still cluttered with employees that are half asleep. I am not really sure what their duties are. Work habits are not very good here. Many of the African Sudanese in the South cling to the habits of the African lion, which lies around and sleeps most of the day, while his lionesses round-up the food and do the dishes so to speak. The entrepreneur spirit is in rather low supply. Many of the businessmen and shopkeepers are Kenyans or Ugandans.

The traditional pastoral and often nomadic lives of many Africans roaming the plains of Sub-Saharan African are not all bad, by any means. You can’t listen to them sing without hearing some happiness there. But it is too easy for those of us not living it day after day to overly romanticize it.

Life at the Afex Riverside Residence at the edge of the Nile remains the same. I continue to be impressed with the timeliness of Deloitte’s team for the morning and after lunch departures of its six cars. In the few minutes before 8:00 am every day except Sunday, thirty or so consultants converge on the car park from several paths and at 8:00 am sharp the cars start pulling out for the drive to the various Ministries (and in my case the Central Bank) at which they work. Often the departure, especially after the lunch break, is virtually simultaneous with all six cars departing from the camp one right behind the other in a caravan. It is an impressive sight.

On irregular trips, the drivers are required to provide a radio report to Base on who is with them and where they are going so that Base knows were every one is. It goes something like this: “Alpha to Base. Alpha to Base…  This is Base.  Leaving Charlie, Charlie, with Bravo D-4 (or whoever) and with, with, and with one “unassigned.”  I am the “unassigned” because I talked Base into not having to carry a bulky two-way radio around, because I almost always travel with colleagues who have one.

A few days back, while eating dinner in the Afex dinning hall—a very pleasant open air facility along the edge of the Nile—a strong gust came up that caused a heavy shower of little black things that covered the dinning room tables, floor, and my plate. I assumed that it was the carcasses of the hundreds of thousands of zapped insects that had given up their lives to the several electric bug killers overhead. I was greatly relieved when I learned that they were little mango seeds that had collected on the canvas roof and were dislodged by the brisk wind.

At dinner this evening our British security officer and another Englishman where telling war stories across the table from me. I was only half listening, but the other Brit’s story about their first-rate French interpreter (they must have been in a French-speaking African country as he is not old enough to be talking about WWII) ended with something like: “he eventually went native on us, drinking red wine and such.” I learn something new every day.

I have been away from home for over a month and need a haircut. My barber for the last 35 years gets very upset if anyone else cuts my hair. During my two month stay in Baghdad in 2004 I was forced to get several and Mike complained for the next two months that it was taking that long to get it back into proper shape. Tuffs of hair now tickle my ears occasionally leading me to fear that a malaria-carrying mosquito has landed there.

Our morning drive from Afex Camp to the Central Bank usually passes a lot of kids on their way to school. The girls and boys dressed in school uniforms is a lovely sight. There is little that is as encouraging and hopeful as seeing young kids smiling on their way to school, especially in a largely illiterate country. So there is hope. There is also little as heart breaking is the face of a child, usually a hungry child, with no hope. The expressionless, unfocused stare of such a child is more than I can bear.

I think that we take hope in American (especially) so for granted that it is hard to imagine a people who have little of it. A great deal of our existence, especially our younger years are filled with the hope that we can build decent enjoyable lives for our selves and our loved ones. What would our youth have been without it? There seems to be a lot of hope in South Sudan now. I hope that it is justified and that it can be sustained.

Should Geithner resign?

Calls for U.S. Treasury Secretary Geithner’s resignation following S&P’s modest downgrading of U.S. government securities are strange. Strange and ignorant. The U.S. Treasury Secretary, our Finance Minister, has nothing to do with our deficit or our debt problem (unless you are blaming him for keeping its maturity shorter than he might). His job is to finance as best he can all of the expenditures our Congress pass and our President sign into law. It would make more sense to call for the resignation of the Congress and the President.

Unlike most countries, in the United States the responsibility to propose a budget to the legislature and to finance whatever the legislature approves are spite between the Office of Management and Budget (OMB) and the Treasury. Most other countries combine the two into their Finance Ministry. The practice else where better aligns incentives to the extent that the level of spending proposed is arrived at in full knowledge of the capacity to finance it.

If calls for Geithner’s resignation are related to debt and deficit problems, the callers need a civics lesson.

Travels in Italy and France

Between a delightful gathering at Robert Mundell’s home at Santa Columbo outside of Siena, Italy (July 7-11), and my return to Juba in newly independent South Sudan, Ito and I have been hanging out in Italy, France.

Mundell’s annual gathering of about 40 economists discussed the reform of the international monetary system. Participants included: Edmond Alphandéry, Domingo Cavallo, Jacob Frenkel, Steve Hanke, Nicolas Krul, Ronald McKinnon, Bill Middendorf II, Aleksei Mozhin, Robert Pringle, to name a few. Christine Lagarde was still on the participant list but didn’t attend having just taken up her duties as the new Managing Director of the IMF, but Rodrigo de Rato, former Managing Director of the IMF and former Vice President for Economic Affairs and Minister of Economy of Spain, was there, as was Min Zhu from China whose appointment as a Deputy Managing Director of the IMF was announced a few days later.

During the two days of discussion, I summarized the paper I had presented earlier at the G-20 High Level Seminar on the Reform of the International Monetary System in Nanjing, China; the Astana Forum, in Astana, Kazakhstan; and the Central Bank of Argentina in Buenos Aires, Argentine on a Real SDR World Currency Board: http://works.bepress.com/warren_coats/23/

From Siena we traveled by train to Milan for two days during which we saw Verdi’s Attila at the world-famous opera house, la Scala (see picture). The opera is not one of Verdi’s best but the la Scala production (co produced with the San Fransisco Opera Company) was outstanding. We had not been to la Scala since its renovation a few years ago: http://en.wikipedia.org/wiki/La_Scala

We traveled on by train to Lyon, France, via Geneva Switzerland to visit Scot Thompson and Louie Pangilinan. Scot has swapped his beautifully compound in Bali with a family with places near Lyon and Paris for the month of July. The house near Lyon is about ten miles north along the Saône River in Cailloux sur Fontaines. The French weather was too cool to use the swimming pool at that house, but Scot and Louie took us on several day trips to some wonderful spots.

The first was to the Château de Fléchères about 20 miles further north. The Château was built from 1606 to 1625. If you are interested you can learn more of its history and see pictures here: http://www.chateaudeflecheres.com/en

In a more easterly direction we visited the medieval village of Perouge, which developed in the 14th and 15th century: http://www.francethisway.com/places/perouges.php

On Monday (July 18) we took the train from Lyon to Avignon in Provence where we were met by Nicolas Krul. He drove us to his beautiful estate in Ménerbes about an hour’s drive southeast of Avignon. Nicolas and I continued the economics discussion we had started during Mundell’s gathering in Siena, and enjoyed two lovely bottles of Sauvignon blanc and a wonderful lunch prepared by his charming wife Meher.

On Tuesday (July 19) Scott and Louie drove us to the other house they had the use of in a southern suburb of Paris. On the way we visited the Basilique de Vézelay and amazing medieval village and cathedral built between the 9th and 13th centuries and from which the 2nd and 3rd Crusades were launched: http://www.burgundytoday.com/historic-places/abbeys-churches/basilique-ste-madeleine.htm

The next day was spent at the Palace and gardens of Versailles, for which no words are adequate: http://en.chateauversailles.fr/homepage. The next three days we explored the usual sights of Paris.

France has changed a lot since I visited it the first time in 1960, over fifty years ago. 1960 was only fifteen years after the end of WWII, which to me at the time seemed centuries earlier. In fact, fifteen years is less than the time from the collapse of the Soviet Union and now, which seems to me like yesterday. Among the pleasant surprises are English (as well as French, of course) announcements on trains and the number of French who can speak English. Even the information booths in rather out-of-the-way places were staffed with people who could speak English and they were very friendly and helpful. At the odd hour of 3:00 pm (between lunch and dinner) we wanted to eat before taking the train from Versailles and Paris. The Brasserie was no longer able to prepare pizza or make a sandwich (out of bread), but happily prepared us a salad with chicken, wanted to know if we were British or American and whether we enjoyed our lunch.

Even Parisians are often friendlier, but not always. Our train from the Eiffel Tower to Saint Michel ended at Invalides because of repairs and we were told that we would need to complete the trip by a bus waiting upstairs. We wandered around underground for a while trying to figure out how and where to go up to the street level. We asked at another Information booth. The lady insisted that we must go “up, UP!” All and all, however, it has been a very nice trip.

We travel to Amsterdam for three days today (Saturday) before Ito returns home and I return to work in Juba, South Sudan. Hopefully I can lose there some of the weight that I gained here.

Our Faltering Economic Recovery

Historically, all recoveries from recessions precipitated by a financial crisis have been long and slow. Our current recovery from the financial crisis of 2008 is starting to look longer and more uncertain than the historical norm. The main reason is the enormous uncertainty over future taxes, spending priorities, and regulations coming from the government. Our looming debt crisis requires significant adjustments in government policies one way or another (see my earlier note on “Thinking about the public debt”) and private investors and consumers naturally retreat in the face of such uncertainty until the course of government policies is settled.

Our high unemployment rate means that aggregate spending (demand) on U.S. output falls short of full employment output. At the highest level of aggregation, economists divide total aggregate demand into the spending by households on current goods and services (Consumption), spending by businesses on capital and capacity improvement (Investment), spending by foreigner (Exports), and spending by the government at all levels (Government).

The Federal Reserve quickly and correctly injected liquidity into the financial system in 2008 – 9, thus containing the scope of the financial crisis. There is nothing left for it to do other than withdraw the extra liquidity in time to avoid inflation when the right time comes.

The government increased its demand for output through several stimulus programs in an effort to fill the demand void created by the retrenchment of private sector Consumption and Investment. Government stimulus required spending without tax financing because tax increases would have further reduced private Consumption and Investment just as tax reductions were meant to increase them. The resulting deficit is unsustainable and has itself become a source of concern. Moreover, some of the government’s increased spending reflected long-term increases in the size of government rather than temporary countercyclical stimulus adding to long-term debt sustainability concerns as well as concerns about government encroachment into undesirable areas. Government stimulus is now being withdrawn.

Recovery requires an increase in Consumption, Investment, and Exports sufficient to match full employment output without the artificial boost of Government stimulus. So what is holding it back?

Until recently, the recovery, slow as it has been, was being lead by an increase in Exports. Over half of our exports go to Europe and recent debt problems in Europe (Greece, Ireland and Portugal) have slowed Europe’s economic recovery and its demand for American exports.

The main factor holding back the recovery of Investment and Consumption is the large uncertainty over the environment in which firms would invest and households would spend. Businesses invest when they think it will be profitable to do so. Significant changes and prospective changes to business and especially financial regulations will take several years to clarify. Until they do it will not be possible to estimate their cost on businesses (and thus consumers) with any accuracy.

Everyone has now accepted the fact that government spending levels and projected levels combined with existing tax revenue and projected revenues are not sustainable. Significant adjustments are unavoidable. The problem is that there is no consensus about what spending to cut and how much to cut it, and what taxes to change and by how much. This is particularly challenging for the big three categories that make up most of the budget (defense, Medicare/Medicaid, and social security).  Businesses find it particularly difficult to estimate the tax treatment new investments might face and follow the sensible path of just waiting to see.

The impasse between Republicans and Democrats in the Congress over the conditions they each require to raise the debt ceiling is in the news and in our faces daily. Few firms are willing to undertake new investments in such an environment.

It is unthinkable that Congress will not raise the debt ceiling, but that does not mean that the game of chicken might not postpone raising it until considerable additional damage has been done to the economy. The stakes are high and neither side will yield easily. The government would quite properly cut expenditures or default on other obligations before they would default on its debt (the U.S. government securities held by households, banks and other firms, as well as other governments around the world). The unquestioned integrity and safety of U.S. government securities is one the critical backbones of the role of the dollar as an international reserve asset and of the dominance of the United States in world financial markets and commerce. But what would it cut?

The expected revenue shortfall for 2011 is $912 billion.[1]Failure to raise the debt ceiling would mean that planned spending would need to be cut by that amount if it could not be borrowed (or taxes increased—but increased revenue from higher tax rates or new taxes, if they materialized at all, would take some time to collect). If the cuts are made in areas other than interest on the existing debt (which for this year is expected to be $287 billion) they will have to include cuts to entitlements like social security and Medicare or defense because discretionary spending (the total Federal budget less defense, entitlements and interest on existing debt) is only $656 billion it cannot be cut below zero. The cuts would need to be greater than the entire defense Department budget of $727 billion. These would be actual cuts, not reductions from planned increases. It is hard to imagine the government defaulting on it monthly social security payments to pensioners or cutting off payments for covered medical treatments or defaulting on salary payments to government employees. Thus the debt ceiling will have to be raised in order to allow a longer more orderly adjustment to spending priorities and levels, which when agreed should be fully financed by an efficient and equitable tax system (see “US Federal Tax Policy”).

Our faltering economy is the result of the government’s inability to get its act together, agree on the rules and on the tax and regulatory environment in which households and businesses operate, consume and invest. No side can force a decision and have their way. It is not reasonable to expect a major reworking of entitlements or the tax system in the next two months, but it is possible to agree on the aggregate size of the cuts required for Republicans to agree to an increase in the debt ceiling so that entitlements, defense and taxes can be more carefully debated over the next year. House Speaker John Boehner’s offer to support a dollar increase in the debt ceiling for every dollar cut from the budget deserves support. But it will only buy badly needed time to more fundamentally reform entitlements, defense spending, and the tax system.

Until these decisions are made and the business environment clarifies and stabilizes, investment and economic recovery will suffer.


[1] Office of Management and Budget, “Budget of the United States Government”

Fund raisers and passive resistance

Political fundraisers have it in their heads (on the basis of evidence no doubt) that sending long letters with stamped return envelopes improves donations. It doesn’t work with me. I resent long fundraising letters, especially with stamped return envelopes, and have established a rule to throw out unread any such letter longer than three pages (most are 7 to 12 pages!!!), including the stamped envelope, though that hurts a bit (as the bastards know full well).

More recently many fundraisers have taken to the telephone. I guess the “don’t call list” doesn’t apply to fundraising. At the end of their spiel, when they ask if I would be willing to contribute X or Y, I invoke another of my self-protective rules and inform them that I never commit to donations on the phone no matter what the cause and I make no exceptions, but I will be happy to review their letter when I receive it (if it is less than three pages). To a man (and occasionally a woman) they then inform me that for the computer they are required to indicate some amount, no matter how small, before a letter can be sent. There must be a marketing study and book that advises this or they have all studied at the same school, because the routine is exactly the same whatever the cause. My innate politeness has led me to waste much of their and my time before the conversation reaches this impasse and I hang up in anger sometimes shouting at them.

I am now pondering whether to simply hang up as soon as their purpose becomes clear or to interrupt with, “I never make or consider donations on the phone” and then hang up before they can explain their required minimum pledge no matter how small.  I welcome your advice or alternative suggestions.

The impact of language on understanding: two small examples

The morning Post is often the catalyst for my blogs. This morning’s edition provoked the following two comments.

According to the Post, in an article reviewing a speech by the justly highly respected Secretary of Defense, “President Obama has pledged to reduce projected spending on national security by $400 billion over the next 12 years, the ‘preponderance of which would come from the Department of Defense,’ Gates said.

That’s on top of $78 billion in long-term spending reductions that the defense secretary announced earlier this year, as well as $100 billion that he said would be cut from wasteful or inefficient programs and reallocated for new weapons and other purposes.”[1]

In the very next sentence the Post says: “All told, the cuts would leave the Pentagon with flat budgets — increasing just below the rate of inflation — until at least 2024.”[2] What does this mean? It means that on the basis of the proposed “cuts” defense spending would increase every year for the next twelve years at a rate slightly below the assumed inflation rate over that period, i.e. real spending would fall slightly. The $478 billion cut in spending over that same period, refers to cuts from currently budgeted or assumed increases over that period. Readers need to pay close attention to understand the meaning of such numbers.

Another article in today’s Post reports on a survey of public attitudes about raising the debt ceiling of the Federal government. The survey finds that more people are concerned about the dangers of raising the debt ceiling than of defaulting on the debt (77% to 73%).[3]  This is strange. The reason they worry about raising the debt ceiling is that it could lead to an even larger federal debt over time. The only reason to worry about that (aside from legitimate concerns about the negative effect on the economy of larger government expenditures, which, of course, could be paid for with tax revenue without an increase the debt) is that if the debt gets too large the government might default. So how is it that people worry more about something that might lead to default than they do about default itself?????

Trying to imagine the consequence of the U.S. government defaulting on its debt is rather like trying to imagine the affect of all out nuclear war. It is unimaginable. A short, temporary default (a failure to pay interest on and repay maturing debt for a few weeks) might not be catastrophic, but it would certainly destroy the high confidence the world now has in owning U.S. debt and would add a significant risk premium to any subsequent U.S. government borrowing. But a longer default would not only lock the U.S. out of domestic and international capital markets (no more borrowing), but would also destroy the dollar’s international reserve currency status (over half of dollar bank notes are held abroad) instantly, and bankrupt thousands of banks and other firms holding U.S. debt. The knock on effects to the world economy (of which we are very much a part) truly are beyond the world’s experience and beyond imagining.

The Rule of Law

The idea that government exists to serve the interests of the people rather than the other way around is modern. It underlies the attitude that Americans and the citizens of other democracies have toward their governments. The essence of this idea and of democracy is not that rulers are chosen by the people; it is that however they are chosen their rule—their powers—are limited by law. The rule of law and the limits it places on the power of the state to interfere with our lives is the essential foundation of our liberties, not voting.

Government involvement in the provision of a service or product is a game changer. There is a centrifugal force that draws private players, “special interests,” into influencing outcomes by influencing politicians and government bureaucrats rather than by competing with better services or products in the market place. This centrifugal force must be continually resisted by limiting what government gets involved in and by insisting on the rule of law. Failure to do so creates a government that looks and behaves more and more like, well, like what we are seeing. America has been exceptional in its success and in its attitudes toward the liberty on which it rests. This exceptionalism is worth fighting (continuously) to preserve.

Richard Lowry & Ramesh Ponnuru explain American exceptionalism as follows:

“It was, to simplify, the most individualistic elements of En­glish society — basically, dissenting low-church Protestants — who came to the eastern seaboard of North America…. America was blessedly unencumbered by an ancien régime. Compared with Europe, it had no church hierarchy, no aristocracy, no entrenched economic interests, no ingrained distaste for commercial activity. It almost entirely lacked the hallmarks of a traditional post-feudal agrarian society. It was as close as you could get to John Locke’s state of nature…. All of this made Amer­ica an outlier compared with England, which was an outlier compared with Europe.

“The late Seymour Martin Lipset defined [the American creed] as liberty, equality (of opportunity and respect), individualism, populism, and laissez-faire economics…. Liberty is the most important element of the creed. To secure it, the Founders set about strictly limiting government within carefully specified bounds.”[1]

War always weakens liberty. When forced, people usually chose security over liberty. A never-ending “War on Terror,” if permitted to continue for too long, threatens to significantly undermine the liberty we are trying to defend. The growing importance of our military might, and the industrial and political interests that feed and support it—the military-industrial complex—will ultimately destroy our exceptionalism. We have been saved so far by our deep tradition of limited use of our military might, our exceptionally capably, honorable, and professional military officers, and the civilian control of their activities. I have written about this theme before: “Eisenhower’s farewell address 50- years later”, “When Values Clash”, “Keep it lean”.

But when our security is threatened we can be tempted to set our principles of respect for human dignity aside. The willingness of some short-sighted individuals to contemplate torture as a tool of warfare in such times illustrates this danger. A number of good articles have been written on this issue. One of the best was by Aryeh Neier: “Enhanced to the point of torture”. Other excellent discussions include: “The Torture Debate”, “Torture is immoral and doesn’t work”, and “Gitmo and us”.

The entertaining Robert Redford movie “The Conspirator,” is a dramatic illustration of the dangers and folly of setting aside the rule of law for what a ruler believes is the interest of the country. The movie depicts (whether historically accurate or not I do not know) the overriding of the important principle of the due process in the “interest” of national healing after the assassination of Abraham Lincoln. I recommend the movie.

Almost everything about government is a slippery slope that can only be prevented by continually challenging the entry and expansion of government into new areas and activities. Some times with proper limits and controls they are justified. More often they are not.


[1] Richard Lowry & Ramesh Ponnuru, “An Exception Debate” National Review Online, May 16, 2010.

The Astana Economic Forum

Hi from Astana, the capital of Kazakhstan.

I am here for the IV Astana Economic Forum at the invitation of Robert Mundell, the Reinventing Bretton Woods Committee, and the Eurasia Economic Club of Scientists. Formally I was invited by Nursultan Nazarbayev, President of the Republic of Kazakhstan, but I sure that he doesn’t know about it, though he will open the meetings. I will continue my year of talking about the IMF’s Special Drawing Right (SDR), which started in Paris in December and continued in Nanjing in March. I will explain my proposal for a global real SDR issued by an international currency board.

My fellow presenters include a number of Nobel Prize winners: Roger Kornberg (Chemistry), Sir James Mirrlees (Economics), John Nash (Economics and who looks nothing like Russell Crowe) and of course Bob Mundell. Other distinguished speakers include Jacob Frenkel, Chairman, JPMorgan Chase International (and my former IMF colleague), Hernando de Soto, economics author and former governor of Peru’s Central Reserve Bank, Richard Cooper, Professor of Economics, Harvard University, and Domingo Cavallo, Former Minister of Economy of Argentina. I am participating with the latter two in a Press Conference on Wednesday.

It is a long way to go for a two-day conference but it should be interesting.

Very Different Visions of Fairness

By temperament and habit I tend to see people as more alike than different. Thus I was struck by how dramatically different Washington Post columnist E. J. Dionne, Jr. sees the world than I do when he was discussing false choices. I think that it is worth illuminating and exploring this difference for what it implies about the nature and role of government we each want.

In his column Monday Dionne quoted himself from a book he had written twenty years ago:

“Women who take time off from their careers to care for young children are routinely ‘punished’ by having their opportunities for promotion reduced,” I wrote. “Is it ‘feminist’ or is it ‘pro-family’ to suggest that this practice is unfair? Is it ‘feminist’ or ‘pro-family’ to contend that this practice shows how little value society really places on the work that parents do?”[1]

I am sure that he finds nothing shocking in these words (or he wouldn’t have quoted them) but I do. Why is it that someone who leaves the labor force for a few years is “punished” by “having their opportunities for promotion reduced?” It is not because they are women or because they are rearing children, because the same would be true for a man (or woman) serving in the Peace Corps for a few years. It is, of course, because to a very large extent companies promote on the basis of productivity (competence, experience, effort, etc). Some of these capacities are gained from actually working (on the job experience) such that a 40-year-old worker who was with the company (or in a particular profession or line of work) for twenty years is likely to be more productive (i.e. worth paying more) than one that took out five years for the Peace Corps (or whatever).  In a competitive market economy companies that do not behave this way will lose out to those that do. In a perfectly competitive economy companies are forced by competitive survival to ignore race, sex, family relationship, or any other factor than productivity.

Dionne takes for granted that this practice, when it results in delayed promotion for a young mother (rather than the Peace Corps volunteer), is unfair and asks whether calling it such is feminist or pro-family (hence the false choice he is discussing). He adds that this practice (promotion based on productivity) “shows how little value society really places on the work that parents do?” By society he presumably means the employers who promote based on productivity, or does he mean a society that would allow employers to do this?

What is the alternative Dionne has in mind? The corrupting seniority system of the civil service would not over come this “unfairness” because time off would reduce seniority. Somehow employers would have to be prevented from basing promotion on productivity in the case of women who take a few years off to raise a family. They might be shamed out of it (social pressure), but the competitive market place that has given us such a high standard of living would punish them for such behavior. The law might forbid such unfairness to mothers. Because the market place will punish firms that promote less productive workers whether the law requires it or not, such a law would create a strong incentive for firms to avoid hiring women in the first place (an unintended consequence).

Mr. Dionne is clearly advocating a society in which employers are expected to promote workers on the basis of how much “society” values them and their non/extra work activities rather than on the basis of their value to the firm (productivity and hence their contribution to our material standard of living).

An example of such a society was the American South in the first half century after the end of slavery. Firms were expected to hire and promote blacks in accordance with social expectations, which looked down on blacks. Mr. Dionne would certainly disagree with the social values that discriminated against blacks but it is an example of how a society functions when it attempts to impose its (the dominate segment’s) non-economic values into economic processes. While racial and ethnic prejudices seem imbedded to some extent in human nature (we would rather hire a cousin than a stranger), competitive market forces work against giving much scope to such biases. Prejudice has a cost in the market place.

Leaving the labor market to raise a family or to service in the Peace Corps is laudable. In the case of raising a family it is essential to the survival of mankind. But it is a personal choice. The person making that choice does so knowing that there will be career consequences. I don’t want to over simplify. The experience of raising a family or of servicing in the Peace Corps may help develop capacities that will promote productivity when the person returns to the labor force. But evaluating that is best left (can only properly be left) with the employer whose bottom line is at stake. Employers can and will make mistakes but at least, unlike bureaucrats administering rules, they have a financial incentive to get it right.

When society (a much overused word) values and benefits from activities that are not rewarded in the market place, they are likely to be undersupplied. Attempting to remove this gap between public and private benefit is challenging and fraught with risks of doing more harm than good. Nature has provided men and women with a strong desire to procreate and raise successful families. But most societies, and certainly ours, have encouraged that propensity and the social benefit of an educated and law-abiding citizenry by, for example, subsidizing elementary education. But we interfere with the efficiency of a competitive labor market at our peril.


[1] E. J. Dionne, Jr. “The real value of false choices”, The Washington Post, April 25, A15

Thinking about the Public Debt

The U.S. Federal Government spent $1.7 trillion dollars last year more than its tax revenue. It had to borrow that amount. This increased the outstanding public debt of the Federal government to 14.2 trillion dollars or 96 percent of GDP. This includes that part owned by the Social Security trust fund and the Federal Reserve but does not include the unfunded liabilities of Medicare, Medicaid and Social Security, which will add an additional $46 trillion to the deficit in present value terms over the next 75 years.

This year’s federal deficit is expected to be 1.4 trillion. Interest payments on this debt are forecast to be $287 billion this year (almost 8% of total outlays) and are expected to grow to three or four times that over the next decade as the stock of debt grows and interest rates rise.

This is not sustainable. Without spending cuts and/or tax increases this amount will not only continue growing without end but will increase as a share of GDP until bond holders are no longer willing to trust the government’s ability to pay the interest required. At that point they will dump U.S. Treasuries and the U.S. will be forced to default. Standard & Poors has already downgraded its “credit outlook” for the U.S. to negative.

All of this is by now well-known as is the fact that there is no longer any choice about the need to cut spending and/or raise taxes. But that is just the beginning of the search for responsible and effective governance by our representatives here in Washington. It makes a big difference which expenditures are cut and which taxes are raised. The deficit will fall and our ability to finance it will increase with the growth of our output/income. Specific spending cuts and tax increases effect income growth differently.

The job of our political representatives is to determine what the government should be doing within the set of things it is permitted to do by the Constitution and the resources the public wishes to make available. Their job is to carefully and wisely set priorities on the use of the limited resources available to them.

David Ignatius provides one of many examples that I strongly agree with: “Today, the United States is allocating about $110 billion annually for the Afghan war, about $3.2 billion for military and economic aid to Pakistan, and about $0.15 billion in special assistance to help Egypt’s democratic revolution. In terms of U.S. national interests, those spending levels don’t make sense. The pyramid is upside down.”[1]

The budget for the Defense Department in 2010, including our several wars, was $664 billion while the State Department (including all foreign aid) was $52 billion.  We have the best fighting machine the world has ever seen and rather mediocre diplomatic capabilities. Better and more extensive use of diplomacy and less use of drones and lesser-guided bombs can often produce better results (improved security for the U.S.). Spending more to develop well-trained (history, culture, language) Foreign Service officers and less to manufacture more munitions might be a good idea. It is hard to imagine that spending less on DOD and more on DOS wouldn’t improve our security for less money.

All spending should pass a strict cost benefit analysis but setting a cap on total spending relative to GDP (e.g., 18 or 19 percent) would be a useful disciplining tool for forcing more careful prioritization. So we must cut deeply but not evenly. We can and should spend less and get more benefit by better prioritizing what is really important to our safety and quality of life. This will not be an easy debate.

The same must be said for taxes. Not all taxes have the same effect on the economic growth that lifts our standard of living and makes a given debt easer to service. And not all taxes are equally fair.  So while the revenue generated by taxes should match the level of government spending over the business cycle, how that revenue is raised is as important as how it is spent.

The primary standards for judging tax systems are neutrality and fairness. Neutrality means that the tax does not distort business and spending decisions so that the allocation of investment and economic resources are not distorted. A neutral tax damages economic growth less than, say, a tax that falls largely on investments. A neutral income tax, for example, treats all sources of income the same.

If tax revenue is raised in ways that do not discourage economic growth, income growth itself will increase tax revenue and reduce a given debt as a share of national income (an indicator of the government’s ability to services it). The arguments in favor of the most neutral possible tax structures are well-known and broadly accepted by economists across the political spectrum. The tax base (whether income or consumption) should be comprehensive making the marginal tax rate as low as possible.

Business income taxation double taxes the same income (by the business and again by the shareholders as individuals) and introduces wasteful and risky corporate behavior in their effort to minimize the tax. Everyone agrees that the corporate profits tax in the U.S. should be lowered more in line with the rates in other countries, but in fact the corporate tax should be abolished. It raises only modest revenue and causes great damage. I favor complete reliance on a flat comprehensive consumption tax (VAT) because it does not tax saving and thus encourages more investment and growth, is simpler to collect and is fairer. [2]

There is less agreement about what is fair. Everyone agrees that the rich should pay more taxes than the poor but how much more. Actually, under the existing tax code those with incomes in the top 1 per cent paid 40 per cent of all income tax revenue in 2006 and earned only 22 per cent of all income, the top 10 per cent paid 71 per cent and the bottom 50 per cent less than 3 per cent.

President Obama thinks that this is not progressive enough and wants to tax high income families even more and the Republicans think it is already too progressive both in terms of fairness and in discouraging investment that promotes faster growth.

A “flat” income tax, the same marginal tax rate for everyone with incomes large enough to pay taxes at all, is the most neutral rate structure when applied to a comprehensive income (or consumption) base. But it is also a good benchmark for discussing fairness. A flat rate means basically that someone with twice the income pays twice as much tax. I consider that fair, but of course our existing rate structure increases with income so that tax payments would more than double when income doubles. Increasing marginal rates is a rather open field. Where should you stop? Clearly our tax system needs to be made more neutral and more fair. The debate over how to do that will not be easy either.


[1] “Time to up the ante on Egypt”, The Washington Post, April 20, 2011, A17.

[2] Warren Coats, “U.S. Federal Tax Policy” , Cayman Financial Review, July 7, 2009